Connect
Start with the tools people use.
National research supports a mobile-first approach. But a shared phone, expensive data or an interrupted connection can still exclude someone. We need assisted routes that preserve each person's control.
About Kapitala
Every community has people who need help, people who can contribute, and organizations that bring them together. Kapitala is the infrastructure we are building to connect them: more accessible borrowing, a habit of saving, and more value shared close to home.
Why this matters
A family faces an unexpected bill. A market vendor needs stock. A driver needs a repair to keep working. When affordable finance is out of reach, a small setback can become a lasting burden.
Communities already have relationships, knowledge and a wish to help. What is missing is a practical way to connect those strengths with capital, responsible lending and financial learning.
The idea
Kapitala is being built to help communities organize financing through lawful, accountable pools. People and organizations could contribute where the structure permits it. Repayments would make capital available for the next person's need.
A business is one way to participate, not the boundary of the idea. Cooperatives, local institutions and the people around them each have a part in a community that can do more together.
Why now
Digital access should open financial possibilities, not just another account.
Connect
National research supports a mobile-first approach. But a shared phone, expensive data or an interrupted connection can still exclude someone. We need assisted routes that preserve each person's control.
Participate
A person should be able to understand a program, ask for help and take part through a lawful community organization. Borrowing is one option, alongside saving, learning and non-debt support.
Share
Our aim is a fairer sharing economy: people helping people under accountable rules. Affordability and local benefit must be demonstrated, after costs and losses, rather than promised by an app.
Mission and vision
Finance should help the people who use it and the community they belong to, not only the organization providing it.
Mission
Vision
The shared benefit
Someone who needs a loan today may help finance another member later. We want both sides of that relationship to benefit.
A quick request through an organization you belong to, with eligibility and repayments set out in advance. Our aim is to make an urgent expense easier to manage, with less paperwork for the member and the organization running the program.
Saving belongs alongside borrowing. We want member education and simple tools to help people set money aside, understand the cost of a loan and make informed choices, with less dependence on loan sharks and other exploitative lenders.
The model is intended to let participating members, as well as the organization, share in the pool's financial results under its rules. Costs, reserves and losses come before any amount available to distribute.
Funding rights and risks depend on the legal instrument. No returns are promised. Member capital, savings and institutional financing must not be treated as one interchangeable balance.
Infrastructure communities can use
Communities should not need to build their own financial software to organize a program for their people.
We are designing guided onboarding around the organization's details, required documents and member list, followed by one place to track requests, balances and repayments. The wider goal includes cooperatives and local community organizations, each under the requirements that apply to it.
Our plan is to charge no software fees until a pool reaches a defined size or member count. Those thresholds and later fees are still being worked out. The intention is to sustain the platform as communities grow, without charging them just to begin. Loan costs are separate from software fees.
We are exploring how repayment history and verified community relationships could help people establish a useful financial record. It must be explainable, correctable and respectful of privacy. No score exists today, and reputation is not collateral or a promise of a larger loan.
These are product goals, not features available to the public yet. Published rules, accountable decisions and a clear correction path. The operating responsibilities must be agreed before a live program opens; this website does not set loan terms or promise outcomes.
Technology in service of people
Checkable rules should not require a public record of someone's whole financial life.
Midnight describes its privacy-focused approach as fourth-generation blockchain. We are researching its selective disclosure and zero-knowledge proofs: ways to reveal only what an interaction needs, or prove a defined fact without revealing the underlying record.
The label is less important than the result. Could a member establish membership without publishing their identity documents? Could a community check a rule without exposing every household's details?
Stays private
What the proof could show
A current membership credential satisfies this program's requirement.
Proposed designStill needs care. The cooperative must issue trustworthy credentials and handle expiry, revocation and recovery. Membership alone does not establish loan eligibility.
Illustration only, not an operating Kapitala feature. No personal data is entered or verified here.
Kapitala is not integrated with Midnight. These are research directions, not features of the initial pilot. Cryptographic proofs do not remove issuer trust, default risk, legal duties or the need for responsible governance.
The path ahead
A working local model comes before a national platform. Open each step to see its purpose and what has to come first.
The first pilot focuses on employee cash advances through participating local businesses and eligible cooperative members. It tests the minimum needed: understandable requests, dependable records, repayments and member education. It does not need every future technology to begin learning.
Technology cannot remove default risk or replace the people responsible for running a pool. It can help make their work accountable. That is the infrastructure we are building.
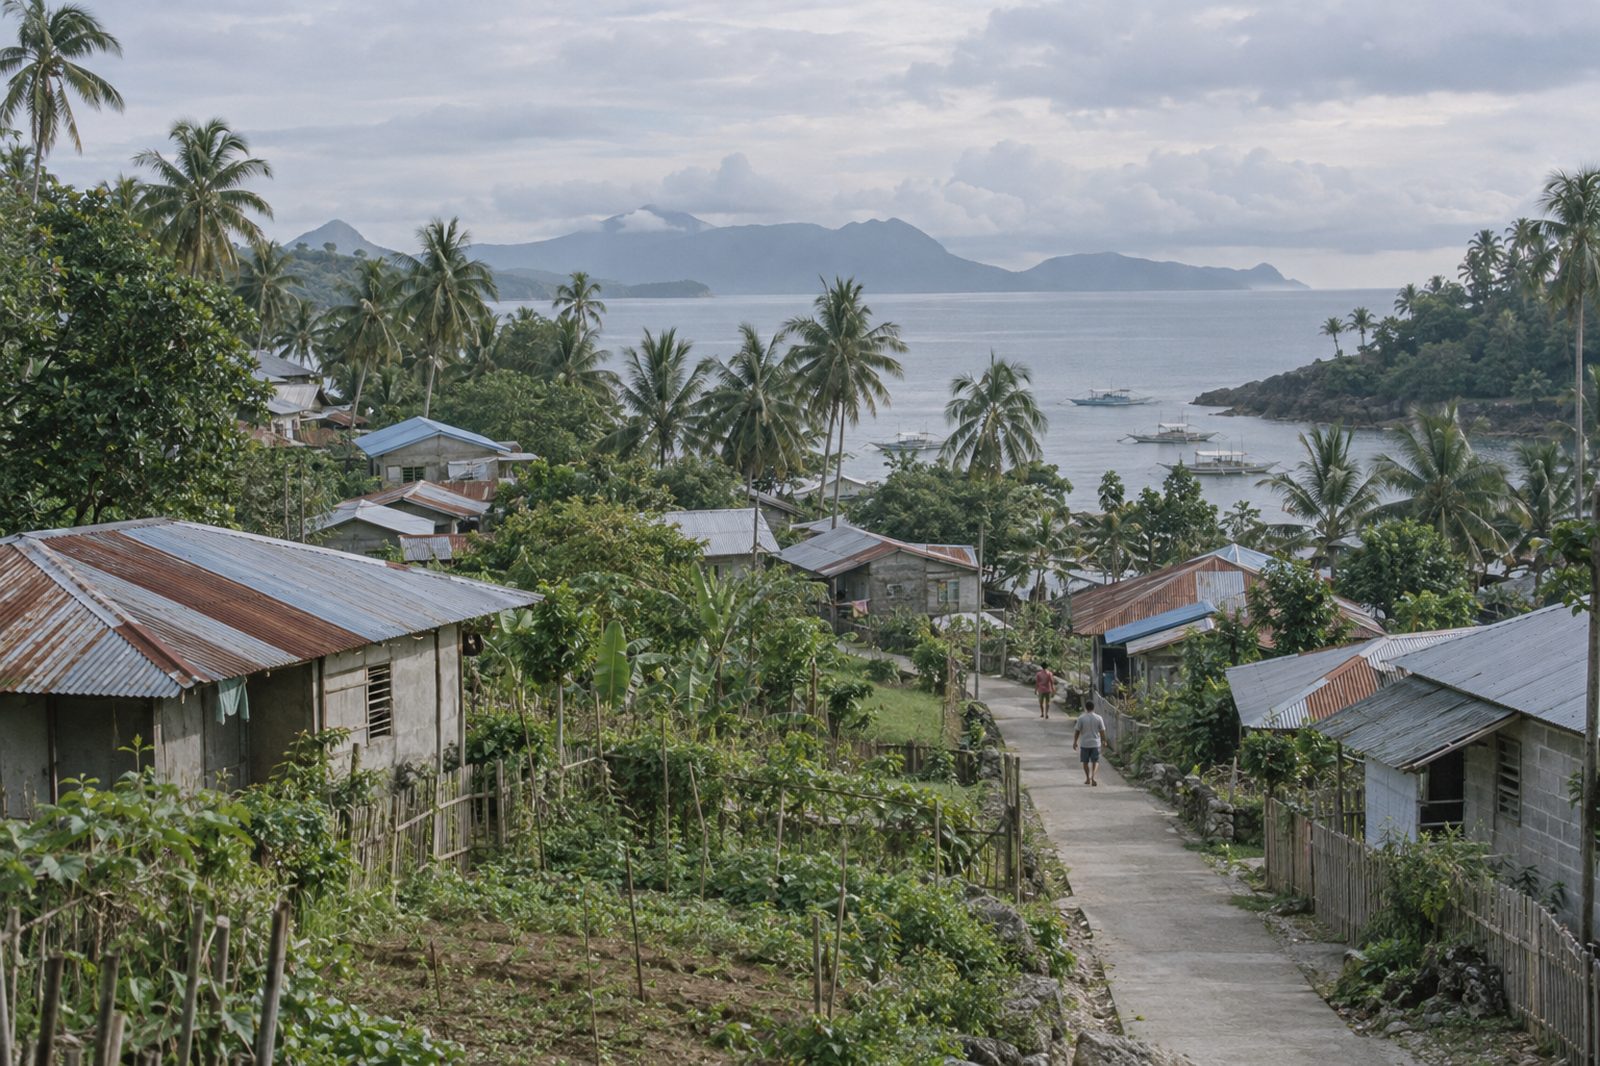
We are developing Kapitala's own software for a first cooperative-operated member program in Siargao. Institutional support is intended; agreements, eligibility and operating arrangements must be settled before launch. This is one practical starting point for a much wider community purpose.
Before lending begins: the operating requirements, member education, fund handling and software checks need to be ready. Registration alone is not that readiness.
Start with recurring employee cash advances and urgent household needs. Test the minimum useful system: member requests, clear records, repayments and financial education. A pilot does not need the full future technology stack to begin learning.
Learn from actual use, repayments, member understanding and the work it takes to run the pool. A pilot must earn the case for expansion.
Use what the pilot teaches us to simplify onboarding and day-to-day operation for other small businesses, cooperatives and community organizations. Local government units are part of the wider ambition, subject to the requirements that apply to them.
Keep access affordable for small communities under the intended software model. Each new setting needs appropriate responsibilities, member protections and a workable operating model, not just an account.
Our long-term direction is an open-source, collaborative project that communities and developers can adapt and improve. The aim is more affordable community finance and better financial education nationwide, with less dependence on exploitative lenders.
Midnight, selective disclosure and portable credentials are research directions, not live integrations. Any adoption must earn its place through privacy, usability, security and legal checks, compared with simpler alternatives.
The first cooperative program is in preparation; membership and lending are not open yet. Program funds will be held by the cooperative, not by this website. Reading the site does not make you a member.
Explore the model, the research direction and the roles people could play as the project develops. Membership and lending remain closed.